
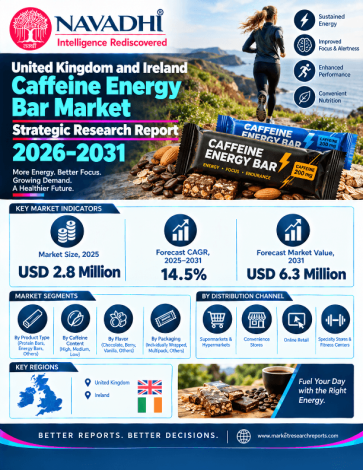
The United Kingdom and Ireland caffeine energy bar market is valued at approximately USD 2.8 million in 2025 and is projected to reach about USD 6.3 million by 2031, a compound annual growth rate of 14.5%. The United Kingdom accounts for about USD 2.5 million and Ireland about USD 0.3 million, shown separately. The market is a small niche inside a much larger energy bar market of about USD 1.7 billion, and the report shows exactly how the niche is derived from it.
Caffeinated bars are on sale in both countries but the range is thin. The report catalogues every product found, including an Irish-made chocolate bar with 80 mg of caffeine stocked in convenience stores, a UK-made oat and fruit bar with 175 mg, an imported caffeinated oat bar with 108 mg and a coffee-based bar with 65 mg. It maps where they are sold, where they are made and what customs data can and cannot show, and it explains why no caffeinated bar has yet reached supermarket shelves.
The market is segmented by bar type into chocolate, oat, nut and fruit, protein and pre-workout, and sports-fuel jelly and chew bars, and by channel into online and direct-to-consumer, specialist sports and health retail, and convenience stores and forecourts. Foods other than drinks with added caffeine must carry a caffeine warning and a per-100 g declaration in Great Britain and the EU; England will bar sales of high-caffeine drinks to under-16s from April 2027; and Ireland is reviewing energy drinks. The report profiles seven companies and includes Porter's Five Forces, PESTLE and SWOT analyses and an outlook to 2031.
Scope of the United Kingdom and Ireland Caffeine Energy Bar Market Strategic Research Report
This report provides market sizing across bar-type and channel segments, region and country splits, a product census, distribution and origin mapping, a competitive landscape of 7 profiled brands, and forecast analysis for 2026-2031.
Segment by Type
Segment by Application
Who Can Use This Report?
Food and sports-nutrition brands and own-label teams assessing a UK or Irish caffeinated bar launch; retailers and distributors deciding whether to range the category; ingredient suppliers of natural caffeine sources; investors and consultants sizing an emerging functional-snack niche; and students and researchers who need UK and Irish data shown separately.
| 1. Executive Summary 1.1 Market Synopsis 1.2 Key Findings 1.3 Market Size Methodology: Top-Down from the Energy Bar Market 2. Industry Overview & Forecast 2.1.1 Market Definition and Scope 2.1.2 Market Value Forecast, 2026-2031 2.1.3 Segment Outlook within the Forecast 2.1.4 Historical Market Review, 2022-2025 2.1.5 Scenario Analysis: Low, Base and High Cases 2.1.6 Product Census: Caffeinated Bars on Sale 2.1.7 Consumption Context: United Kingdom and Ireland 2.1.8 Forecast Reliability and Reading the Numbers 3. Market Segmentation by Type 3.1 Market Segmentation by Type 3.1.1 Market by Type Overview 3.1.2 Chocolate Caffeine Energy Bars 3.1.3 Oat, Nut and Fruit Caffeine Energy Bars 3.1.4 Protein and Pre-Workout Caffeine Bars 3.1.5 Sports-Fuel Jelly and Chew Bars 3.1.6 Type Segment Outlook 4. Market Segmentation by Application 4.1 Market Segmentation by Application 4.1.1 Market by Application Overview 4.1.2 Online Stores and Direct-to-Consumer 4.1.3 Specialist Sports, Health and Other Retail 4.1.4 Convenience Stores and Forecourts 4.1.5 Supermarkets and Hypermarkets: The Missing Channel 4.1.6 Channel Outlook and Implications 5. Regional Market Forecast United Kingdom Ireland 6. Country-Level Market Forecast 6.1 United Kingdom 6.1.1 England 6.1.2 Scotland 6.1.3 Wales 6.1.4 Northern Ireland 6.2 Ireland 6.2.1 Republic of Ireland 7. Growth Drivers & Inhibitors 7.1 Growth Drivers & Inhibitors 7.1.1 Market Drivers 7.1.2 Market Restraints 7.1.3 Regulation and Labelling 7.1.4 Impact Assessment 7.1.5 Opportunities & White-Space Analysis 7.1.6 Analyst Perspective 8. Key Company Profiles 8.1 RYSE Chocolate 8.1.1 Company Overview 8.1.2 Key Products & Segments 8.1.3 Financial Performance (2023–2025) 8.1.4 Business Strategy 8.1.5 SWOT Analysis 8.1.6 Strategic Implications (2025–2031) 8.2 VOOM Nutrition 8.2.1 Company Overview 8.2.2 Key Products & Segments 8.2.3 Financial Performance (2023–2025) 8.2.4 Business Strategy 8.2.5 SWOT Analysis 8.2.6 Strategic Implications (2025–2031) 8.3 Naak 8.3.1 Company Overview 8.3.2 Key Products & Segments 8.3.3 Financial Performance (2023–2025) 8.3.4 Business Strategy 8.3.5 SWOT Analysis 8.3.6 Strategic Implications (2025–2031) 8.4 Peeroton GmbH 8.4.1 Company Overview 8.4.2 Key Products & Segments 8.4.3 Financial Performance (2023–2025) 8.4.4 Business Strategy 8.4.5 SWOT Analysis 8.4.6 Strategic Implications (2025–2031) 8.5 LSP Sporternaehrung GmbH 8.5.1 Company Overview 8.5.2 Key Products & Segments 8.5.3 Financial Performance (2023–2025) 8.5.4 Business Strategy 8.5.5 SWOT Analysis 8.5.6 Strategic Implications (2025–2031) 8.6 Mondelez International, Inc. 8.6.1 Company Overview 8.6.2 Key Products & Segments 8.6.3 Financial Performance (2023–2025) 8.6.4 Business Strategy 8.6.5 SWOT Analysis 8.6.6 Strategic Implications (2025–2031) 8.7 Veloforte 8.7.1 Company Overview 8.7.2 Key Products & Segments 8.7.3 Financial Performance (2023–2025) 8.7.4 Business Strategy 8.7.5 SWOT Analysis 8.7.6 Strategic Implications (2025–2031) 9. Competitive Landscape 9.1 Competitive Landscape Overview 9.2 Competitive Intensity Assessment 9.3 Key Player Strategies & Positioning 9.4 Competitive Dynamics & Strategic Outlook 9.4.1 Emerging Competitive Threats 9.4.2 Consolidation versus Fragmentation 9.4.3 Competitive Response Matrix 9.4.4 Strategic Recommendations, 2025-2031 10. Porter's Five Forces Analysis 10.1 Threat of New Entrants 10.2 Bargaining Power of Buyers 10.3 Bargaining Power of Suppliers 10.4 Threat of Substitutes 10.5 Competitive Rivalry 11. PESTLE Analysis 11.1.1 Political 11.1.2 Economic 11.1.3 Social 11.1.4 Technological 11.1.5 Legal and Regulatory 11.1.6 Environmental 11.1.7 Strategic Implications of the PESTLE Analysis 12. SWOT Analysis 12.1 SWOT Analysis 12.1.1 Overview and Analytical Frame 12.1.2 Market-Level Strengths 12.1.2.1 Strength: Large, Growing Parent Market with Established Buyers 12.1.2.2 Strength: Deeply Habitual Caffeine Consumption 12.1.2.3 Strength: Natural Caffeine and Clean-Label Credentials 12.1.2.4 Strength: Strong Sports and Fitness Demand Base 12.1.2.5 Strength: A Proven Convenience-Channel Pathway in Ireland 12.1.2.6 Strength: Format Differentiation Across Four Product Types 12.1.3 Market-Level Weaknesses 12.1.3.1 Weakness: Shallow Distribution and Limited Mainstream Visibility 12.1.3.2 Weakness: Low Brand Concentration and Subscale Players 12.1.3.3 Weakness: Dose Constraints Relative to Guidance Limits 12.1.3.4 Weakness: Substitution by Established Caffeine Formats 12.1.3.5 Weakness: Reliance on Imports for Several Specialist Products 12.1.3.6 Weakness: Poor Market Data Visibility 12.1.4 Strategic Opportunities 12.1.4.1 Opportunity: Major-Brand or Own-Label Supermarket Entry 12.1.4.2 Opportunity: Scaling the Convenience-Store Model 12.1.4.3 Opportunity: Cross-Selling Through Specialist and Online Channels 12.1.4.4 Opportunity: Import Substitution and Local Manufacturing 12.1.4.5 Opportunity: Formulation Innovation and Premiumisation 12.1.4.6 Opportunity: Regulatory Tailwind Against Energy Drinks 12.1.4.7 Opportunity: Growing Workplace and Productivity Positioning 12.1.5 External Threats 12.1.5.1 Threat: Tightening Caffeine Regulation and Labelling Burden 12.1.5.2 Threat: HFSS Restrictions on Less-Healthy Bars 12.1.5.3 Threat: Health and Safety Perception of Caffeine 12.1.5.4 Threat: Competition from Entrenched Substitutes and Large Incumbents 12.1.5.5 Threat: Economic Pressure on Discretionary Functional Snacks 12.1.5.6 Threat: Supply-Chain and Stock Reliability 12.1.5.7 Threat: Measurement and Investment Uncertainty 12.1.6 SWOT Synthesis and Strategic Implications 13. Future Trends & Outlook 13.1 Future Trends & Outlook 13.1.1 Natural-Caffeine Sources and Clean-Label Positioning 13.1.2 Major-Brand and Own-Label Entry 13.1.3 Regulatory Direction: Age Limits and Labelling 13.1.4 Long-Term Market Outlook (2032-2035) 13.1.5 Investment & Partnership Outlook List of Exhibits Exhibit 2.1: Forecast of United Kingdom and Ireland Caffeine Energy Bar (in USD Mn) Exhibit 2.2: Forecast of United Kingdom (in USD Mn) Exhibit 2.3: Forecast of Ireland (in USD Mn) Exhibit 2.4: Forecast of Global Market YoY Growth Rate & CAGR Summary (in %) Exhibit 3.5: Forecast of Chocolate Caffeine Energy Bars (in USD Mn) Exhibit 3.6: Forecast of Oat, Nut and Fruit Caffeine Energy Bars (in USD Mn) Exhibit 3.7: Forecast of Protein and Pre-Workout Caffeine Bars (in USD Mn) Exhibit 3.8: Forecast of Sports-Fuel Jelly and Chew Bars (in USD Mn) Exhibit 4.9: Forecast of Online Stores and Direct-to-Consumer (in USD Mn) Exhibit 4.10: Forecast of Specialist Sports, Health and Other Retail (in USD Mn) Exhibit 4.11: Forecast of Convenience Stores and Forecourts (in USD Mn) Exhibit 6.12: Forecast of United Kingdom (in USD Mn) Exhibit 6.13: Forecast of England (in USD Mn) Exhibit 6.14: Forecast of Scotland (in USD Mn) Exhibit 6.15: Forecast of Wales (in USD Mn) Exhibit 6.16: Forecast of Northern Ireland (in USD Mn) Exhibit 6.17: Forecast of Ireland (in USD Mn) Exhibit 6.18: Forecast of Republic of Ireland (in USD Mn) |
*If Applicable.
NAVADHI is a market research company that helps global firms differentiate themselves, break market entry barriers, track their investments, develop business strategies and plan for future by providing actionable market research intelligence that helps them succeed.